After an accident, storm, or other unexpected loss, you may depend on your insurance claim to help cover repairs and other eligible expenses. Naturally, one of the first questions you may ask is: How long will it take to receive payment?
The answer depends on several factors, including the type of claim, the extent of the damage, the evidence available, your insurance policy, and the requirements in your state.
Some straightforward claims may be resolved relatively quickly, while complex claims involving significant damage, disputed responsibility, or additional investigations can take weeks or months.
In this guide, we’ll explain how long insurance claims may take, what can slow down the process, and what you can do to help move your claim forward.
How Long Does an Insurance Claim Usually Take?
There is no single timeline that applies to every insurance claim. The time needed to investigate, approve, and pay a claim varies by insurer, policy, type of loss, and state requirements.
A simple claim with clear documentation may be settled faster than one involving extensive repairs or disagreements about coverage.
Here are some general examples:
- Minor auto damage: A straightforward claim may be resolved in days or a few weeks, depending on inspections, estimates, and approvals.
- Major car accidents: Claims involving serious injuries, multiple vehicles, or disputed responsibility may take considerably longer.
- Minor home damage: A claim involving limited damage and clear evidence may move relatively quickly.
- Major homeowners claims: Significant fire, storm, or structural damage may require detailed inspections, contractor estimates, and additional investigation.
- Disputed claims: Claims involving disagreements about coverage or the amount payable can take longer, especially if an appeal or formal complaint is necessary.
These are general illustrations, not guaranteed processing times. Your insurer and state may have specific requirements that affect the timeline.
How Long Does a Car Insurance Claim Take?
Auto insurance claims vary according to the accident, the type of coverage involved, and whether anyone disputes what happened.
Minor car accident claims
A claim involving minor vehicle damage may be resolved relatively quickly when the facts are clear, the damage is easy to assess, and the necessary documents are available.
The process may take longer if the insurer needs an inspection, additional photographs, or a revised repair estimate.
Claims involving major vehicle damage
Serious damage may require a more detailed inspection to determine the cost of repairs or whether the vehicle is a total loss.
If the vehicle is declared a total loss, the insurer may need to calculate its value, review the vehicle’s condition, and resolve any questions about a loan or lease.
These steps can add time to the process.
Claims involving injuries
An auto claim involving injuries may take longer than a property-damage-only claim. Medical treatment, injury assessments, questions about responsibility, and negotiations over eligible expenses may all affect the timeline.
Some injury claims cannot be fully evaluated until the person’s medical condition and treatment needs are clearer.
Claims involving another driver
If another driver is involved, the insurers may need to review statements, photographs, police reports, and other evidence before determining responsibility.
If liability is disputed, the investigation and settlement process may take longer.
For a better understanding of the protection available under different policies, read our guide to what car insurance covers.
How Long Does a Homeowners Insurance Claim Take?
Homeowners insurance claims also vary widely in duration. The size and cause of the loss can make a substantial difference.
Minor home damage
Claims involving limited damage, such as a covered incident affecting a small part of the home, may be easier to assess than major structural losses.
If the damage is well documented and the policy coverage is clear, the insurer may be able to make a decision sooner.
Roof damage claims
Roof claims may require an inspection to determine the cause and extent of the damage. The insurer may need to distinguish between sudden damage caused by a covered event and problems associated with wear, deterioration, or maintenance.
Disagreements over the cause of damage can delay a decision.
Fire and major structural damage
Large losses may require multiple inspections, specialist reports, detailed repair estimates, and coordination with contractors.
The insurer may also need to review additional living expenses if the home is temporarily uninhabitable and the policy provides that coverage.
Claims after widespread disasters
When hurricanes, wildfires, severe storms, or other disasters affect many properties, insurers and contractors may experience unusually high demand.
Inspection schedules, access to damaged properties, material shortages, and the volume of claims can all affect the time needed to resolve a claim.
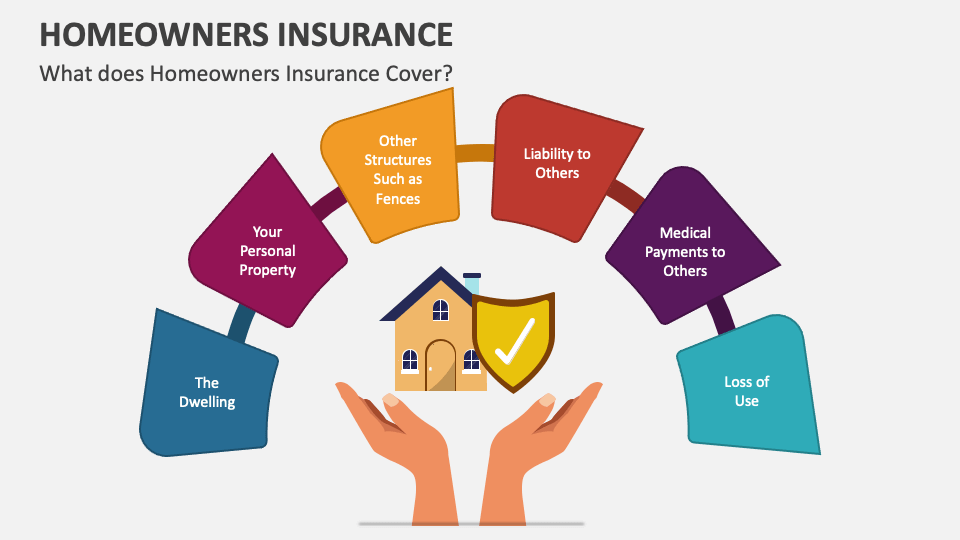
To understand the types of protection a homeowners policy may provide, read what homeowners insurance covers.
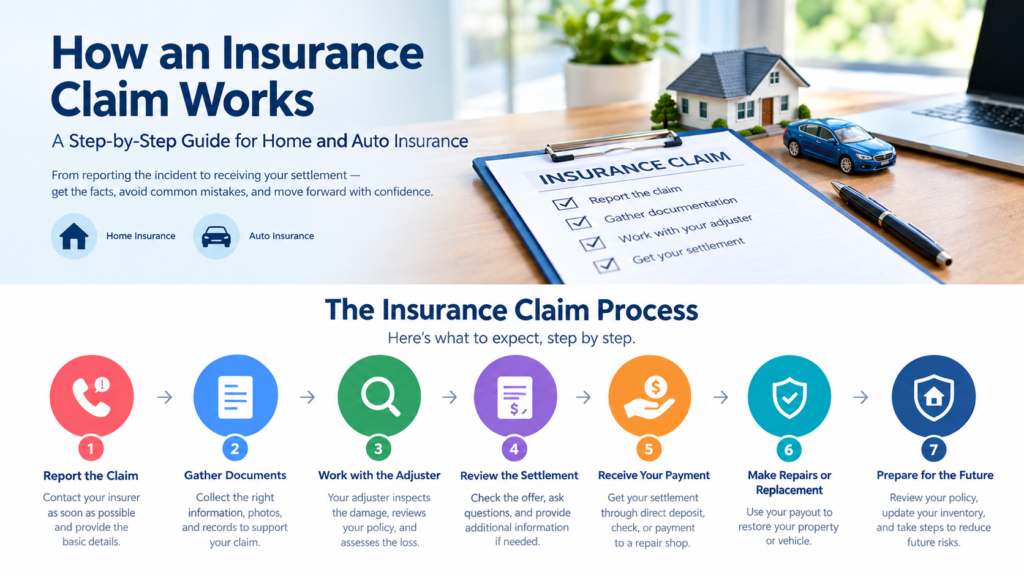
What Happens During the Insurance Claim Process?
Understanding the steps involved can help you see why a claim may take time.
Step 1: Reporting the incident
You notify your insurer about the accident or loss and provide basic information, such as when it occurred and what was damaged.
Reporting requirements and deadlines vary, so follow the instructions in your policy.
Step 2: Opening the claim
The insurer records the claim, provides a claim number, and explains the next steps. A claims adjuster may be assigned to review the circumstances and evaluate the loss.
Step 3: Investigating the claim
The insurer reviews the information provided and may request photographs, receipts, statements, reports, or other evidence.
For some claims, an inspection or specialist assessment may be necessary.
Step 4: Assessing coverage and costs
The insurer evaluates whether the loss is covered and estimates the eligible payment based on the policy’s terms, limits, and deductible.
The insurer may ask for additional information if the cause or extent of the damage is unclear.
Step 5: Making a decision
Once the necessary review is complete, the insurer may approve the claim, approve part of it, request further information, or deny it.
If the claim is approved, the insurer explains the payment or settlement process.
Step 6: Payment and repairs
Payment timing depends on the insurer’s procedures, the type of claim, and any remaining requirements.
In some cases, payments may be issued in stages. For example, a homeowners claim may involve an initial payment followed by additional payments as eligible repairs are completed and documented.
For a more detailed overview, read our guide to how an insurance claim works. Confirm that this URL matches your existing article’s actual slug before publishing.
What Can Delay an Insurance Claim?
Several issues can extend the time needed to resolve a claim.
1. Missing documents
If the insurer needs repair estimates, photographs, receipts, or other records and does not receive them promptly, the review may be delayed.
What you can do: Ask the adjuster for a clear list of outstanding documents and submit them as soon as reasonably possible.
2. Disputes about responsibility
In auto claims, insurers may disagree about who caused an accident. In homeowners claims, they may disagree about what caused the damage or whether the cause is covered.
What you can do: Provide accurate information, photographs, witness details where available, and any relevant reports.
3. Extensive damage
Major damage often requires more detailed inspections and cost estimates. Some repairs may also require specialist contractors.
What you can do: Keep records of inspections, estimates, and communications. Ask the insurer which assessments are still outstanding.
4. High claim volumes
After a major storm or disaster, insurers may receive many claims at once. This can affect inspection availability and processing schedules.
What you can do: Keep your claim number accessible, respond to requests promptly, and ask for updates about the next expected step.
5. Coverage questions
The insurer may need to determine whether the incident is covered, whether an exclusion applies, or how much the policy will pay.
What you can do: Review your policy and ask the adjuster to explain any coverage questions in writing.
6. Contractor or repair delays
Even after a claim is approved, repairs may be delayed because of contractor availability, parts shortages, weather, or building material costs.
What you can do: Maintain communication with the repair provider and insurer, and keep written records of revised estimates and expected completion dates.
7. Incomplete or disputed estimates
If you disagree with the repair estimate, additional inspections or discussions may be needed before the eligible amount is settled.
What you can do: Request an itemized estimate and provide supporting documentation from a qualified repair professional if you believe important work has been omitted.
How Can You Help Your Insurance Claim Move Faster?
You cannot control every part of the claims process, but you can take steps to reduce avoidable delays.
Report the loss promptly. Follow your policy’s reporting requirements and provide accurate details about the incident.
Document the damage. Take photographs or videos where it is safe to do so, and keep receipts for eligible emergency expenses.
Submit complete information. Respond to document requests and check that the information you provide is accurate and consistent.
Keep communication organized. Save emails, letters, claim numbers, and notes from phone calls.
Ask about outstanding steps. Rather than asking only when the claim will be finished, ask what needs to happen before the next decision can be made.
Keep receipts and estimates. These documents can help the insurer evaluate repair costs and determine eligible expenses.
Review your policy. Understanding your deductible, limits, and coverage can help you identify questions early.
Do not delay urgent repairs needed to protect people or prevent further damage. Follow safety guidance, document the situation where possible, and contact your insurer for instructions.
How Can You Check the Status of an Insurance Claim?
Most insurers provide a way to check claim progress, although the available options vary.
You may be able to use an online account, a mobile app, email, or a claims phone line.
When contacting the insurer, have your claim number ready and ask specific questions, such as:
- Has the initial investigation been completed?
- Are any documents still missing?
- Has an inspection been scheduled?
- Is the repair estimate approved?
- Is there a coverage issue that needs to be resolved?
- What is the next step, and who is responsible for it?
- Is there an estimated date for the next update or decision?
An insurer may not be able to provide a precise final payment date while the investigation is ongoing. However, knowing the outstanding steps can help you understand where things stand.
What If Your Insurance Claim Is Taking Too Long?
If your claim seems to be stalled, begin by contacting the adjuster or claims department. Ask what is causing the delay and whether the insurer needs anything from you.
Keep a written record of the response and any expected follow-up dates.
If you cannot obtain a meaningful update, consider using the insurer’s formal customer complaint process. You may also contact your state’s insurance department to ask about claim-handling requirements and available consumer assistance.
State laws may establish standards for acknowledging claims, investigating losses, communicating decisions, or making payments. These requirements vary, and a delay does not automatically mean the insurer has violated the law.
If the dispute involves a substantial amount of money or a potential legal deadline, consider seeking advice from a qualified attorney in your state.
How Long After Approval Does an Insurance Company Pay?
Claim approval and payment are not always the same event. Some insurers can issue payment soon after approving a straightforward claim, while other claims require additional paperwork or settlement steps.
For example, a homeowners claim may involve checks payable to more than one party, such as the homeowner and a mortgage lender. Certain claims may also require documentation before additional funds are released.
Ask your insurer:
- Whether the claim is fully approved.
- Whether any documents or signatures are still required.
- How the payment will be issued.
- Whether the deductible has been applied.
- Whether the payment covers the full approved amount or is an initial payment.
- When you should expect the next update.
Payment deadlines may be governed by state law or policy requirements, so check the rules applicable to your situation.
Frequently Asked Questions
Can an insurance claim take several months?
Yes. Complex claims involving serious injuries, major property damage, disputed responsibility, or detailed coverage investigations can take months. Straightforward claims may be resolved much sooner.
Does an insurance company have a deadline to settle a claim?
Many states have insurance claim-handling rules, but the specific deadlines and requirements differ. Check your state’s insurance department for applicable guidance.
Does a claim take longer if I use my own insurance?
Not necessarily. Using your own insurer may allow certain claims to move forward without waiting for another insurer to accept responsibility. However, the timing depends on the circumstances, coverage, and any investigation required.
Can I start repairs before my insurance claim is approved?
It depends on the situation and your insurer’s requirements. Necessary emergency work may be appropriate to protect people or prevent further damage, but major repairs can complicate the evaluation if the damage is not documented. Photograph the damage, keep receipts, and contact your insurer before starting non-urgent major repairs when possible.
What if my claim is approved but I have not received payment?
Contact the insurer and ask whether any paperwork, approvals, or other requirements remain outstanding. Request an explanation of the payment status and the expected next step.
Can I complain if my insurance claim is delayed?
You can contact the insurer’s complaint department and, where appropriate, your state insurance department. Whether a delay violates any requirement depends on the facts and applicable state rules.
Final Thoughts
The time required to settle an insurance claim depends on the type of loss, the complexity of the investigation, the documents available, and the insurer’s obligations under your policy and state law.
Straightforward claims may be resolved relatively quickly, while major or disputed losses can take much longer. You can help avoid unnecessary delays by reporting the incident promptly, submitting complete information, keeping records, and communicating regularly with your insurer.
If your claim appears to be stalled, ask what remains outstanding and what you can reasonably expect next. If the delay continues without a clear explanation, review your insurer’s complaint process and consider contacting your state’s insurance department.
Disclaimer: This article is for general educational purposes only and does not provide insurance, legal, or financial advice. Claim timelines, payment requirements, and consumer protections vary by insurer, policy, and state. Contact your insurer or state insurance department for guidance about your circumstances.